Analyzing the Importance of ESG Report Verification from the Mistakes of Nongfu Spring ESG Report
With the arrival of 2023, the compilation and release of corporate CSR/ESG reports has also ushered in a peak stage.
Recently, the latest richest company in China, the well-known Chinese company Nongfu Spring, released an ESG sustainable development report that sparked a huge discussion in the circle of friends;
http://www.nongfuspring.com/sustainability.html
Nongfu Spring has just released its ESG report for 2021. Because Nongfu Spring is listed on the Hong Kong Stock Exchange, its ESG report is written in accordance with the ESG disclosure requirements of the Hong Kong Stock Exchange.
According to the report, Nongfu Spring has won honors such as National Green Factory and National Green Supply Chain Management Enterprise. Nongfu Spring also has some practical cases in the fields of water conservation and carbon emissions. However, in terms of water conservation and carbon emission reduction, Nongfu Spring only set relative indicators such as emission intensity, but did not set absolute emission reduction targets.
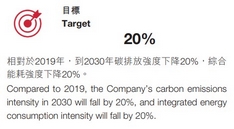
There is no absolute emission reduction target, which means that if Nongfu Spring’s business continues to expand in the future, its total emissions will continue to increase. There is no absolute value reduction target, enterprises can establish carbon peak and carbon neutral goals based on the scientific carbon target SBTi, and guide enterprises to practice climate change actions from a development perspective and a strategic height.
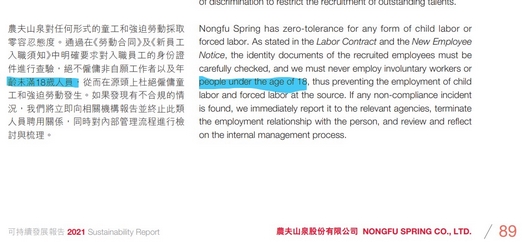
There is also an obvious mistake in the report. The editor of the report probably wanted to explain that the company does not employ child labor, but he/she obviously did not understand whether the age definition of child labor is 16 or 18. The report blatantly stated that it refuses to recruit employees under the age of 18, but our national labor law stipulates that employees aged 16-18 can be recruited. Such small mistakes reflect Nongfu Spring’s lack of understanding of labor laws and its unprofessional social responsibility module; this is also a portrayal of the current ESG “overheating” phenomenon;
Many so-called ESG professionals talk about ESG without even being familiar with and mastering the knowledge of Social Social Responsibility in ESG.
As an organization focusing on ESG training, report compilation and verification, Leverage would like to tell you the importance of ESG report content and data compliance;
ESG reporting verification can help companies communicate while reducing the risk of non-compliance;
If Nongfu Spring has invited a professional third-party organization to conduct the verification of the report, this kind of mistake will definitely be identified and corrected;
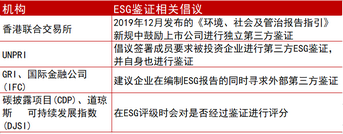
From December 2019, the Hong Kong Stock Exchange issued the "Environmental, Social and Governance Reporting Guidelines" to encourage listed companies to conduct independent third-party ESG verification of their ESG reports.
The Current State of ESG Assurance
As of December 31, 2021, there were 4,681 A-share listed companies, of which 1,412 companies disclosed the 2021 ESG report, with a disclosure rate of 30%. However, there are only 54 companies with certified ESG reports, and the certified rate is 3.8%.
In contrast, the disclosure rate of independent ESG reports of Hong Kong stocks is relatively low (109, corresponding to 4.26%), but 69 companies have been certified, and the certification rate exceeds 63%.
In the sci-tech innovation board of the subdivision of listed companies, 95 sci-tech innovation board companies have separately disclosed ESG reports, but have not certified ESG reports. Therefore, they are still a blank market for ESG assurance business.
Definition of ESG Assurance
According to the definition of IAASB (International Standards on Auditing and Forensics), ESG report forensics means that the forensics service provider states a conclusion on a forensics object (such as the key data disclosed in the ESG report) according to the forensics work criteria, so as to enhance the degree of trust of the expected users other than the responsible party on the output results of the forensics object.
In order to avoid conflicts of interest, the assurance service provider should be a third-party professional organization, so that effective assurance can ensure the impartiality and reliability of its reports.
With the increasing intensity of corporate ESG information disclosure, regulators and asset managers have begun to focus on the reliability of information disclosure, and ESG third-party assurance has received more attention.
Table: Financial Institutions and Their Related Initiatives on ESG Assurance
The Significance of ESG Assurance
As the importance of ESG-related performance continues to emerge, investors and stakeholders have higher expectations for reliable, consistent and high-quality ESG information and data, requiring that the information and data in ESG reports stand up to scrutiny.
We found that more and more companies are actively seeking independent third-party organizations to verify their ESG reports.
Employing a third-party institution to verify an enterprise's ESG report can improve the credibility and transparency of the information and data disclosed in the ESG report, effectively improve the credibility and transparency of the ESG report (or its key data), help listed companies to more effectively disclose ESG information and improve the quality of ESG information disclosure, so as to better respond to the concerns of stakeholders such as foreign investors, and to help investors and other prospective users of the report obtain ESG information more effectively.
On the other hand, ESG assurance can also help companies review the information disclosure process and content from the perspective of an independent third party to ensure quality.
Listed companies can clarify the disclosure caliber of ESG data, judge whether the ESG-related internal control system design is rigorous, whether the control activities are effectively implemented, and whether there are loopholes in the current management system, strengthen the collection and management of ESG data and information, and standardize the ESG work management process, improve management loopholes, accelerate the establishment of an ESG management system, strengthen corresponding risk management, and improve the overall risk management level.
In April 2021, the European Commission adopted the draft of the Corporate Sustainability Reporting Directive (CSRD), which puts forward mandatory audit requirements for ESG disclosure information.
In March 2022, the U.S. SEC also put forward a consultation draft to enhance the standardization of climate disclosure, requiring companies to disclose scope 1 and scope 2 emission data to be verified and certified by an independent third party.
The proportion of listed companies around the world that provide assurance for ESG information continues to rise.
Which international standards are ESG reports based on?
Currently more authoritative standards and guidelines include: AA1000 compiled by ISEA (Social and Ethical Accountability Association), and ISAE3000 compiled by IAASB (International Auditing and Assurance Standards Board). Among them, AA1000 is the first authoritative verification standard with ESG information disclosure as the main body, and has a wider scope of application. Since the promulgation of this standard, the number of international companies conducting verification according to this standard and issuing ESG verification reports has gradually increased.

Shanghai Leverage Supply Chain Management Co., Ltd. has been approved as an AA1000 sustainable development (ESG) report verification agency. Leverage will cooperate with AccountAbility to provide professional verification services in the disclosure of sustainable information and corporate responsibility information, so as to provide customers with confidence in coping with sustainable development challenges and investors' scrutiny.
Advantages of AA1000AS V3 Effective Application
► Draw conclusions on the quality, rigor, and consistency of the organization's overall management practices, as well as performance on the four AA1000AP (2018) principles of inclusiveness, materiality, responsiveness, and impact.
► Assist reporting organizations in obtaining assurance on overall sustainability performance, including scope of management and reporting, through the application of AA1000AP (2018)
► Ensure that the reporting organization's objectives, disclosures and sustainability management are stakeholder-centred.
► Provides proven and internationally recognized sustainability assurance methodologies.
► Complement other international and national assurance standards and frameworks.
► Compatible with other international, national, sectoral and/or theme-driven sustainability-related standards, frameworks and guidelines.
► Build trust and credibility for the reliability and quality of disclosures reporting on an organization's sustainability performance.
► Generate externally assured information to effectively support governance practices, organizational decision-making and risk management.
Verification Process
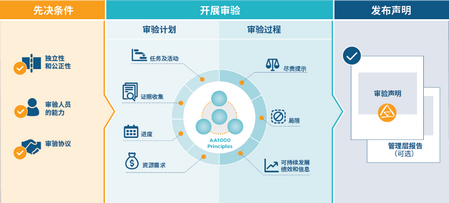
It is expected that enterprises will pay attention to the accuracy of content and data while telling the story of corporate ESG practice, so as to avoid unnecessary trouble and loss;
Leave the professional work to professional people, and let us work together to tell the "ESG" story of Chinese companies.
Leverage is a clean, transparent and responsible third-party supply chain management service company. A member unit of the Life Cycle Green Management Professional Committee, as well as a member unit of many international organizations such as UNGC, UNEP, AWS, SAI, etc. As an AA1000 sustainable development (ESG) report verification agency, Leverage will use the professional knowledge of its own team to provide professional verification services for corporate sustainability reports.
ISO Management System Certification | Service Certification | Product Certification | Product Inspection and Testing Service | Enterprise ESG Strategy Consulting | ESG Report Preparation | OCI Marine Plastic Recycling Certification | Carbon Verificaion for Enterprises | Carbon Footprint Verificaion for Product | Carbon Neutrality Project Customization
If you want to know more information, please contact us:
■ Shanghai :
Leverage Limited (Shanghai) Co., Ltd.
Address: Room 402, No 2. Building, No .1328, Hengnan Rd, Shanghai, China
Phone: + 86 21 64067720
Email: cs@leveragelimited.com
■ Hongkong :
Leverage Global Limited
Address: Room 1318-19, Hollywood Plaza, 610 Nathan Road, Mongkok, Kowloon, Hong Kong
我们的资质或实践:
·SAI 批准的 SA8000 认证机构(NO.046)
·中国合格评定国家认可委员会检验鉴定机构CNAS (NO.IB0605)
·国际劳工组织(ILO)SCORE 可持续发展项目许可机构
·中国海关总署批准的检验鉴定机构(No.683)
·HIGG FEM环境项目验证机构(NO.131899)
·公益金融联盟(GSFN)创始发起单位
·UNGC联合国契约组织成员
·CNCA中国国家认证认可监督管理委员会认证机构
·中国出入境检验检疫协会合规工作委员会成员
·浙江省国际贸易协会数字化专业委员会联合发起单位及专家委员
· UNEP LCI 联合国环境规划署生命周期倡议成员
·长三角一带一路国际认证联盟服务机构
·长三角绿色低碳发展行动共同体成员
·全生命周期绿色管理专业委员会成员单位
·中国企业气候行动CCCA成员
·AA1000可持续发展(ESG)报告验证机构
· 科学碳目标倡议(SBTi)成员
· TCFD气候相关财务信息披露工作组支持者
·EPD环境产品声明中国认可机构
·联合国责任投资原则组织(UN PRI)签署机构
·IIAF 国际反舞弊协会成员
·上海市企业法律顾问协会 理事单位
·上海市可持续发展研究会国际标准化专业委员会
·国家“绿色制造体系”第三方评价机构
·零碳工厂评价认证服务机构
·上海市绿色低碳服务机构
·制药供应链负责任倡议PSCI审核机构
·全球电子协会IPC1401 ESG管理体系先学伙伴
·EcoVadis 认可的核心咨询合作伙伴
·中华环保联合会ESG专委会委员单位
·IFRS认可的第三方服务机构
·IAASB认可的第三方服务机构
我们的服务:
Leverage在全球范围内为客户提供站式的解决方案和系列增值服务,包括但不限于如审核、认证、验证、验货、绿色供应链管理、培训、Ecovadis/CDP/NQC-SAQ/SBTi/CSA/MSCI 技术咨询、ILO SCORE 企业可持续发展培训项目、Higg FEM 环境验证项目、服务认证、产品认证、ISO 管理体系认证 (ISO9001 质量管理体系、ISO14001 环境管理体系、ISO45001 职业健康安全管理体系、ISO37001 反贿赂管理体系 、 ISO37301 合规管理体系 、GB/T 39604 社会责任管理体系、ISO20400 可持续采购绩效评估、ISO28000 供应链安全管理体系认证 等) 、 SA8000 社会责任审核 、神秘访客服务、OCI 海洋塑料循环回收认证、定制化可持续发展解决方案和 ESG 报告编制及评级提升、AA1000可持续发展(ESG/TCFD)报告鉴证、ISO14064 和 ISO14067 等温室气体碳盘查、碳足迹、碳管理体系建设、碳中和认证、碳中和路线图披露等相关可持续发展服务。
我们的客户:
我们已经为350多家国内外著名品牌提供了专业服务,其中包括正泰集团、金风科技、华为、晶科能源、瑞可达、中材科技、上下、台达、丰田汽车、奇瑞、晨光、中车、阳光能源、冠捷、臻臣、翔泰、Gildan、The Very Group, The Manufactured Network, ARCO, MuscleSquad, WALMART, GAP, H&M, ZARA, NIKE, ADIDAS, ONLY, PVH, VF, TARGET, Costco, ALDI, DUNELM, ASDA, Coles, JCPenney, COLES, NewLook, B&Q, BAREFOOT, MONSOON, George, Waitrose, RiverIsland, HALFORDS, JohnLewis, Hallmark等。
我们的服务网络:
我们也在包括日本、韩国、越南、柬埔寨、孟加拉、缅甸、马来西亚、印度尼西亚、斯里兰卡、巴基斯坦、美国、英国、意大利等国家设立分公司或代表处,相信能为供应链上游的利益相关方提供更为全面的解决方案。
Related Posts

欢迎联系我们
Leverage上海总部 :
地址:上海市闵行区恒南路1328号2号楼M02室
电话: +86 21 64067720
邮箱:info@leveragelimited.com
业务联系:
Murphy Fei 13917452486
Aron Qu 13917794381
Weber Hu 18817921025
其他事宜联系人:
技术支持: Joyce Gu 13601755765
投诉及建议: Murphy Fei 13917452486
廉政事宜: Aron Qu 13917794381
匿名举报邮箱:
compliance@leveragelimited.com
【关注公众号】
Our Partners